What Is the Risk of Reducing Car Insurance Coverage
Reducing coverage means you, not the insurer, pay for whatever your old limits used to cover.
Free to compare
The risk is that costs don't disappear, they just move to you
Insurance works by transferring a cost you can't predict to a company that spreads it across many people. When you lower a limit or drop a coverage, you're not making that cost go away. You're deciding that if it happens, you'll pay it yourself, out of savings or future income. For a family that just took on a car seat, a bigger car payment, or a stretch on one income, that's a different bet than it was before.
The coverages most parents think about cutting are liability limits, collision, and medical payments or personal injury protection. Liability pays for the other side if you're at fault, so cutting it risks your own assets in a lawsuit, not just a repair bill. Collision and comprehensive pay for your own car, so dropping them only makes sense if you could replace the car in cash without blinking. Medical payments and PIP often cover your passengers, including a child in a car seat, for injuries regardless of fault, so that's the one many new parents don't realize they're touching when they cut costs.
What varies is which coverages are required, which are optional, and which auto-include things like replacing a car seat after an accident. Some states require PIP or no-fault coverage, others don't. Some insurers replace car seats automatically after any crash where the seat was in use, others only after an at-fault accident above a certain severity. Check your state's minimum requirements and your insurer's specific rules on car seat replacement and passenger medical coverage before you change anything.
The cases where reducing coverage works out fine are the boring ones. A second car that's older, driven rarely, with an owner who has savings to cover its full value and no loan on it, can often drop collision and comprehensive safely. A single adult with no dependents and modest assets carries less lawsuit risk than a parent supporting a family. Your situation has changed, so the math that used to apply may not anymore.
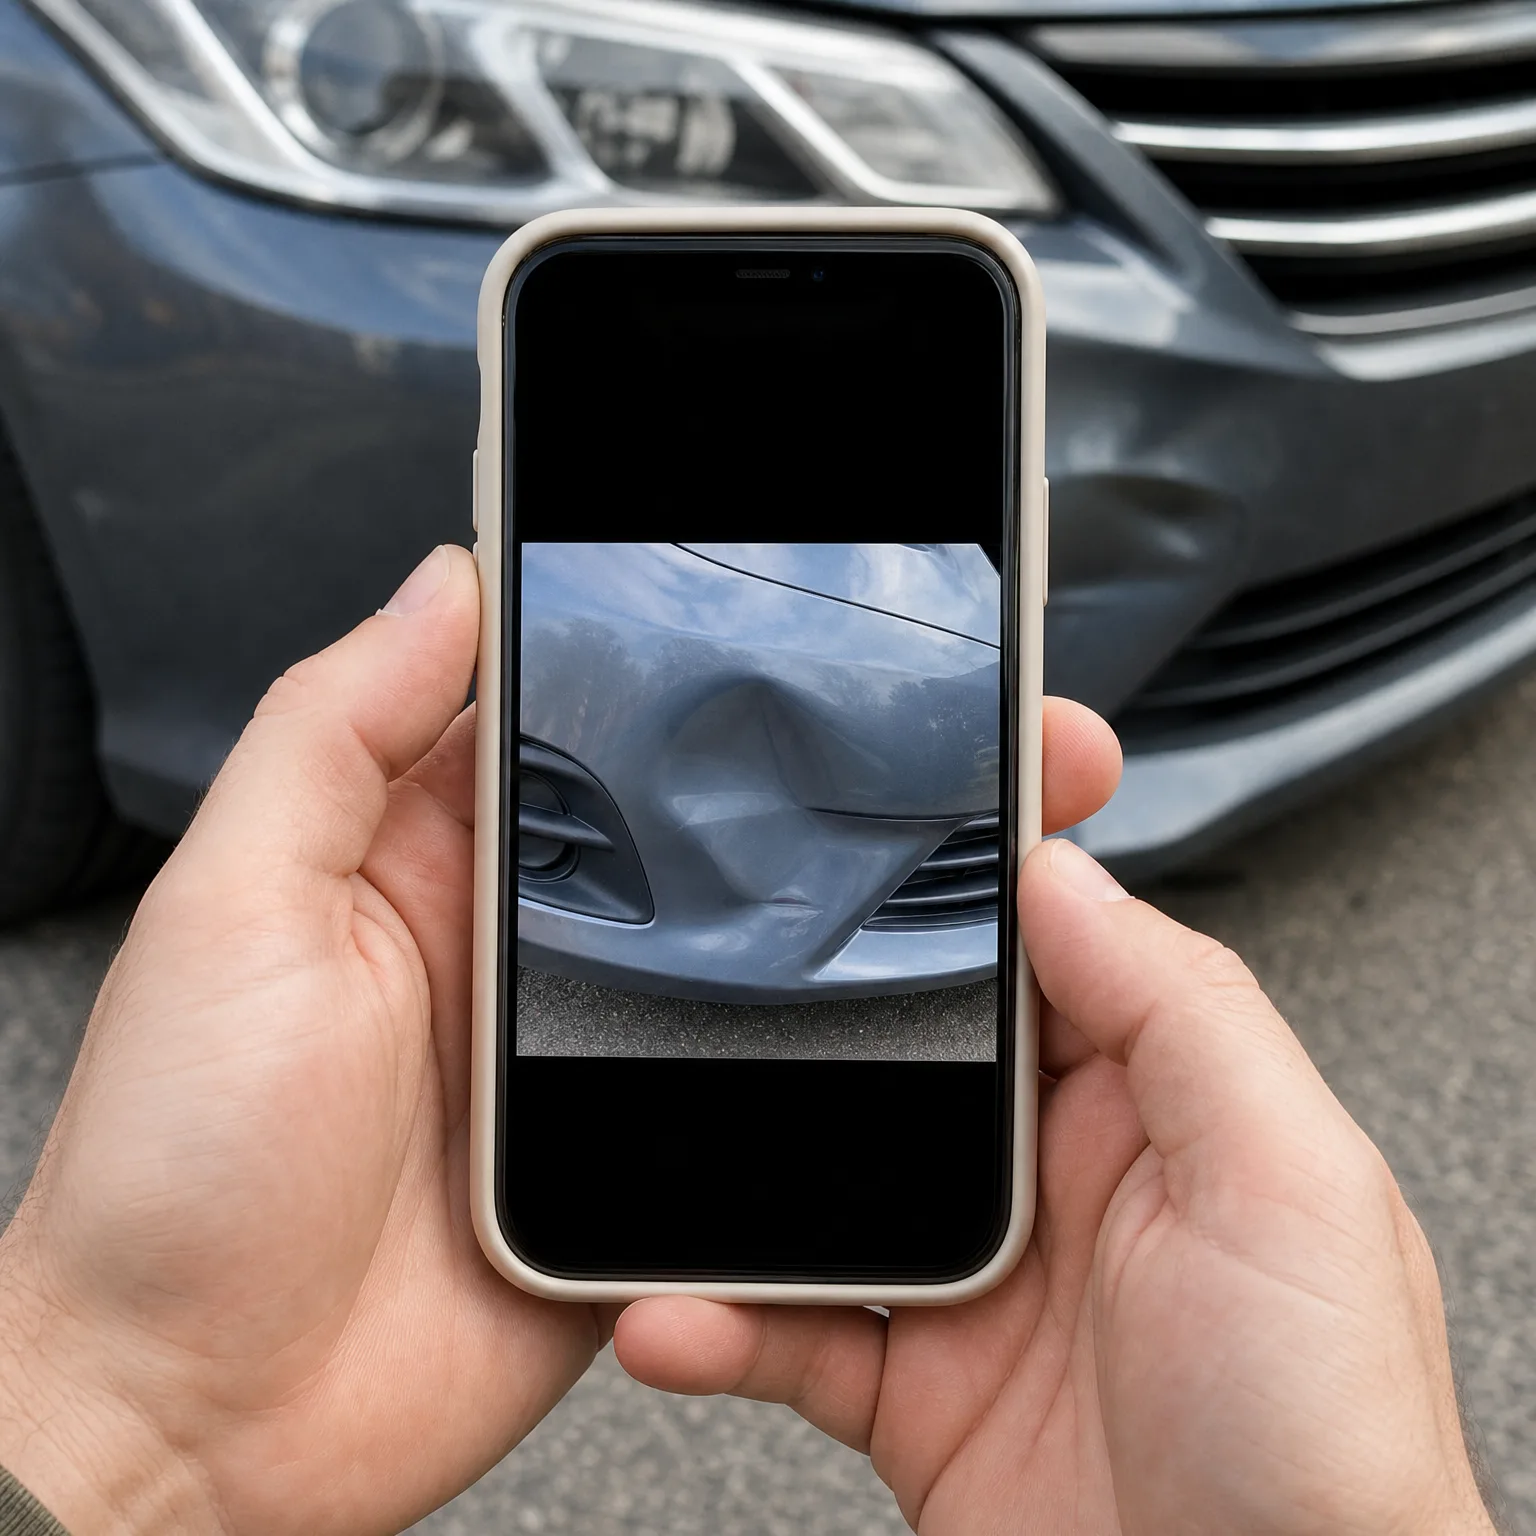
These are the cuts that matter most for a growing family
- Liability limits This pays for the other side if you cause an accident, not for you. Keep this at or above what your assets and future earnings could cover in a lawsuit.
- Medical payments or PIP This often covers your passengers, including a child in a car seat, regardless of fault. Check what it pays out before lowering or dropping it.
- Collision coverage This pays to repair or replace your own car after an accident you caused. Only drop this if you could replace the car in cash without hardship.
- Uninsured motorist coverage This protects you and your family if the other driver has no insurance or not enough. With more people depending on your income, this matters more now.
- Car seat replacement Many policies replace a car seat after any crash, but rules differ by insurer. Ask directly what triggers replacement before you need it.
The coverage you cut doesn't vanish as a risk, it just becomes a bill only you can pay.
Compare quotes now that you know which coverages to keep and which to question.
Should you lower your limits now to save money
If you do
You'll pay less each month right away, which helps if you're on one income during leave. But if an accident happens, you'll cover the gap yourself, in legal costs, medical bills, or a car you can't replace. That gap is often larger than new parents expect, especially with a child now riding with you.
If you don't
You'll keep paying the higher premium for now, which strains a tighter budget. In exchange, a crash won't turn into a financial emergency on top of an injury or a damaged car. You keep the option to lower coverage later, once income stabilizes or the car is paid off.
Does car insurance cover a car seat after an accident?
Many insurers replace a car seat after any accident where it was installed, regardless of fault, but this isn't universal. Some only replace it after an at-fault crash above a certain damage threshold, and some require you to ask rather than doing it automatically. Call your insurer and ask specifically what triggers replacement and whether you need a police report or repair estimate to claim it. If your policy doesn't cover this, you may need a rider or should budget for a new seat yourself.
Should I add my baby to my car insurance policy?
You don't add an infant to your policy the way you would a teen driver, since they're not driving, but you should tell your insurer about the new dependent. This can affect your medical payments or PIP coverage limits, since more people are now riding in the car regularly. It may also be a good time to review your liability limits, since a lawsuit now affects a family with a child, not just you. Ask your insurer directly whether a new dependent changes your recommended coverage.
How much liability coverage do I need with a new baby?
Enough to cover what a lawsuit could take from you, which now includes protecting income a child depends on, not just your own assets. There's no universal number, since it depends on your assets, your state's rules, and what you could realistically lose in a judgment. A common approach is to match liability limits to your net worth plus some cushion for future earnings. Ask an agent to walk through your specific assets and state requirements before deciding on a figure.