Can I Be Insured on Two Different Cars
Yes, you can carry insurance on two different cars at once, whether they're on one policy or two separate ones.
Free to compare
Insurance follows the car and the driver, not a single policy slot
Auto insurance exists to cover a specific vehicle and the people who drive it, so nothing stops you from insuring more than one car at the same time. Most insurers actually prefer you keep multiple vehicles on one policy, since it simplifies billing and often lowers the cost per car. But you're not required to use the same insurer or the same policy for both.
The reason this matters right now is timing. If you're trading up to a bigger car for the baby but keeping the old one for a while, or if one parent is driving less during leave, you may need both vehicles covered simultaneously, even if only for a short overlap. That overlap is completely normal and insurers handle it every day.
Where it gets more complicated is when the two cars are garaged in different states, owned by different people, or used by someone outside your household. A car a grandparent drives regularly, or a vehicle kept at a second home, may need its own policy rather than joining yours. Lending your car to someone long-term, or a car seat living permanently in a vehicle you don't legally own, can also change who needs to be listed as a driver.
The practical difference is just bookkeeping. Two policies means two bills, two renewal dates, and separate claims histories. One multi-car policy means shared paperwork but one set of coverage decisions. Either way, the coverage itself protects the same things: the car, the people in it, and anyone else involved in an accident.
Should I put both cars on one policy or keep them separate?
For most families in your situation, one policy covering both cars is simpler and usually cheaper, since insurers often discount multi-car households and you only track one renewal date and one set of coverage limits.
Separate policies make more sense when the cars are owned by different people, garaged in different states, or when one car is rarely driven and you want very different coverage on it, like liability-only on an older vehicle you're about to sell. If you're about to swap vehicles anyway, ask your insurer how they handle the short overlap before you decide which route to take.
Compare quotes for covering both vehicles together, now that you know how combining or separating them actually works.
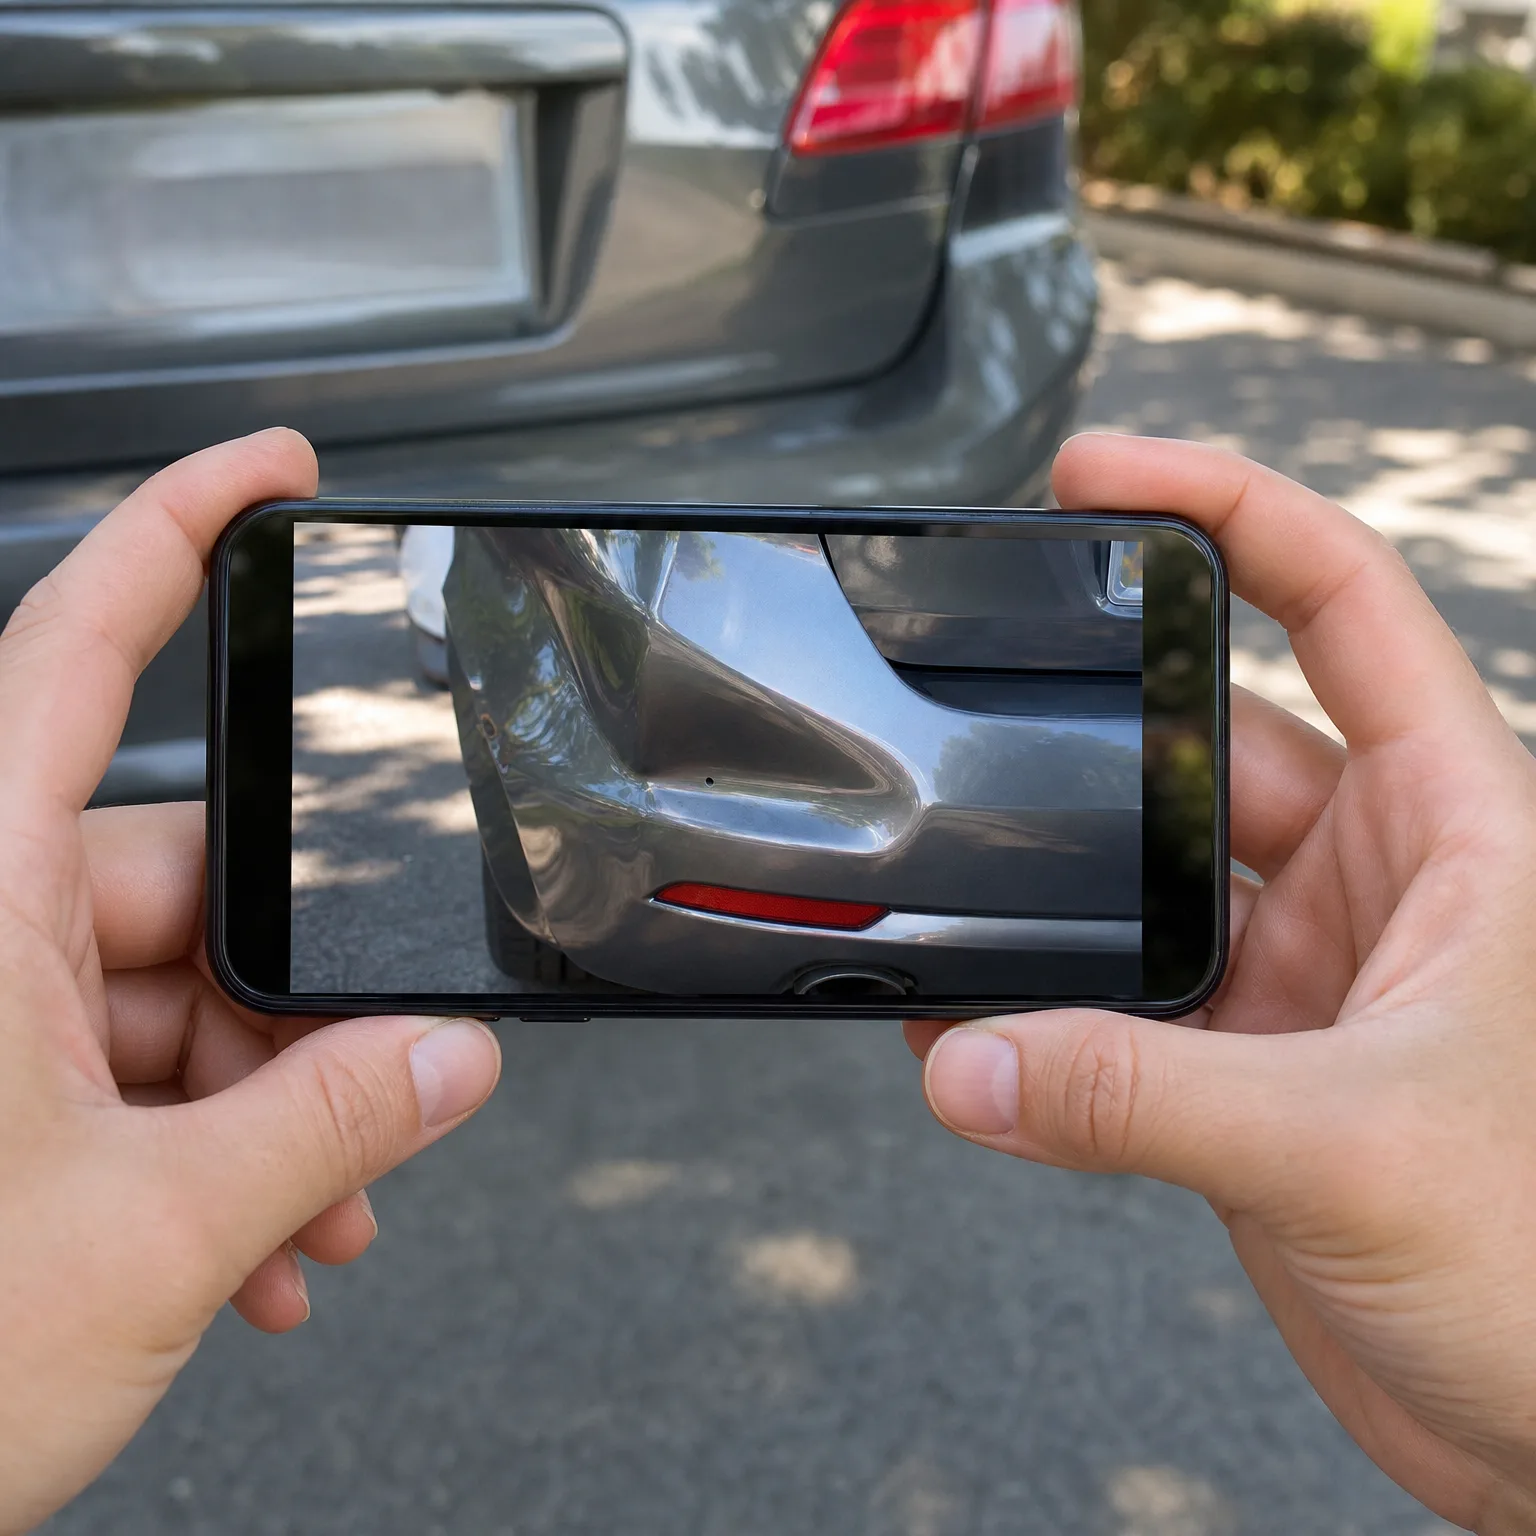
What to confirm before you insure the second car
- Same household or not If both cars are kept at your address and driven by people in your family, they usually qualify for one combined policy. Confirm this with your insurer before assuming it.
- Who's listed as a driver Each car needs every regular driver listed, including a new spouse or a grandparent who drives it often. Leaving someone off can affect a claim later.
- Coverage levels per car You can carry higher liability on the car with the car seat and lighter coverage on an older vehicle. Decide this car by car, not as one blanket choice.
- Gaps during a trade-in If you're swapping vehicles, ask how the insurer handles the days both cars exist. Most will cover a short overlap automatically, but confirm the window.
- State rules on multiple policies Some states treat multi-vehicle households differently for minimum coverage or discounts. Check what your state requires before finalizing either policy.
Keeping the old car during a trade-in
A couple expecting their second child traded their sedan for an SUV with more back seat room for two car seats. The dealership deal closed before they'd sold the old sedan, so for about three weeks they owned both cars outright. They called their insurer before driving either one off the lot, worried that the new car wouldn't be covered or that they'd be paying for insurance on a car they no longer needed.
Their insurer added the SUV to the existing policy and kept the sedan listed until it sold, charging for both but applying a multi-car discount that offset part of the cost. When the sedan sold three weeks later, they called again to remove it and the policy adjusted immediately. They ended up paying slightly more for those few weeks but avoided any gap in coverage during the handoff, which mattered more to them than the extra cost given how often they were driving both cars with a newborn at home.
Can I insure a car I don't legally own?
Yes, but only if you have the owner's permission and typically need to show an insurable interest, meaning you drive it regularly or are financially responsible for it. If the car belongs to a family member, some insurers require the owner to be on the policy too or to add you as a listed driver. Check with the insurer directly since rules vary by company and by state, and this comes up often with shared or hand-me-down family vehicles.
Does adding a second car affect my rates on the first one?
It can, usually by lowering them through a multi-car discount rather than raising them. Insurers often reward combining vehicles because it increases the amount of business they keep with you. The exception is if the second car belongs to a driver with a worse record, since that can raise the combined policy's overall rate depending on how the insurer calculates household risk.
What happens to car seat coverage if I switch which car I drive most?
Car seat replacement coverage after an accident usually follows the car involved in the claim, not a specific driver or seat. If you move the seat between vehicles, what matters is which car was in the accident when the claim is filed. Check your policy wording, since some insurers cover car seat replacement automatically after any accident while others require you to add it specifically.