What Happens if Your Totaled Car Is Worth Less Than You Owe
You owe your lender the gap between what the car was worth and what you still owed, unless gap coverage picks it up.
Free to compare
Why the payout and your loan balance don't match
Your insurer pays what the car was worth right before the crash, not what you paid for it or what you still owe. Cars lose value faster than most loans get paid down, especially in the first couple of years, so there's often a gap between the two numbers no matter how carefully you've kept up with payments.
That gap is yours to cover unless you bought gap coverage, which is a separate add on built exactly for this situation. Without it, your auto policy has done its job once it pays the car's value. The loan is a separate contract with your lender, and the insurer isn't part of it.
This hits hardest with small down payments, long loan terms, or trading in negative equity from a previous car into the new loan. All three make the loan shrink slower than the car's value drops, which widens the gap right when you'd least want it to.
How your state handles the payout timeline and whether your lender can demand the balance immediately can vary, so check your loan agreement and ask your insurer how they calculate value in a total loss.
What to check before you accept the payout
- Your loan payoff amount Call your lender for the exact payoff figure, not your last statement balance. This is the number you're comparing the insurer's offer against.
- Whether you have gap coverage Check your policy declarations page or ask your agent directly. If you have it, it covers the difference, if not, you'll need another plan.
- How the insurer valued the car Ask for the valuation report and compare it to similar cars for sale nearby. You can dispute the number if it looks low.
- Payment options with your lender Ask if they'll let you pay the gap over time instead of all at once. Some lenders are flexible if you ask before the payoff is due.
- Rules in your state Some states limit how lenders can collect a deficiency balance. A quick call to your lender or a local consumer agency will tell you what applies.
Can you still get gap coverage after the accident already happened?
No. Gap coverage has to be in place before the accident, because it's designed to cover a loss that already occurred under your policy. Once the car is totaled, that window has closed, and no insurer will sell you coverage for a claim that's already happened.
If you're in this position now, the gap becomes a debt to negotiate with your lender rather than an insurance claim. For your next car, if you're financing with a small down payment or a long loan term, buying gap coverage from the start avoids this exact problem. It's one of the few add ons worth deciding on upfront rather than after you see how fast the car depreciates.
Know your gap risk, then compare quotes that include gap coverage so your next payout actually covers the loan.
A loan that outpaced the car's value
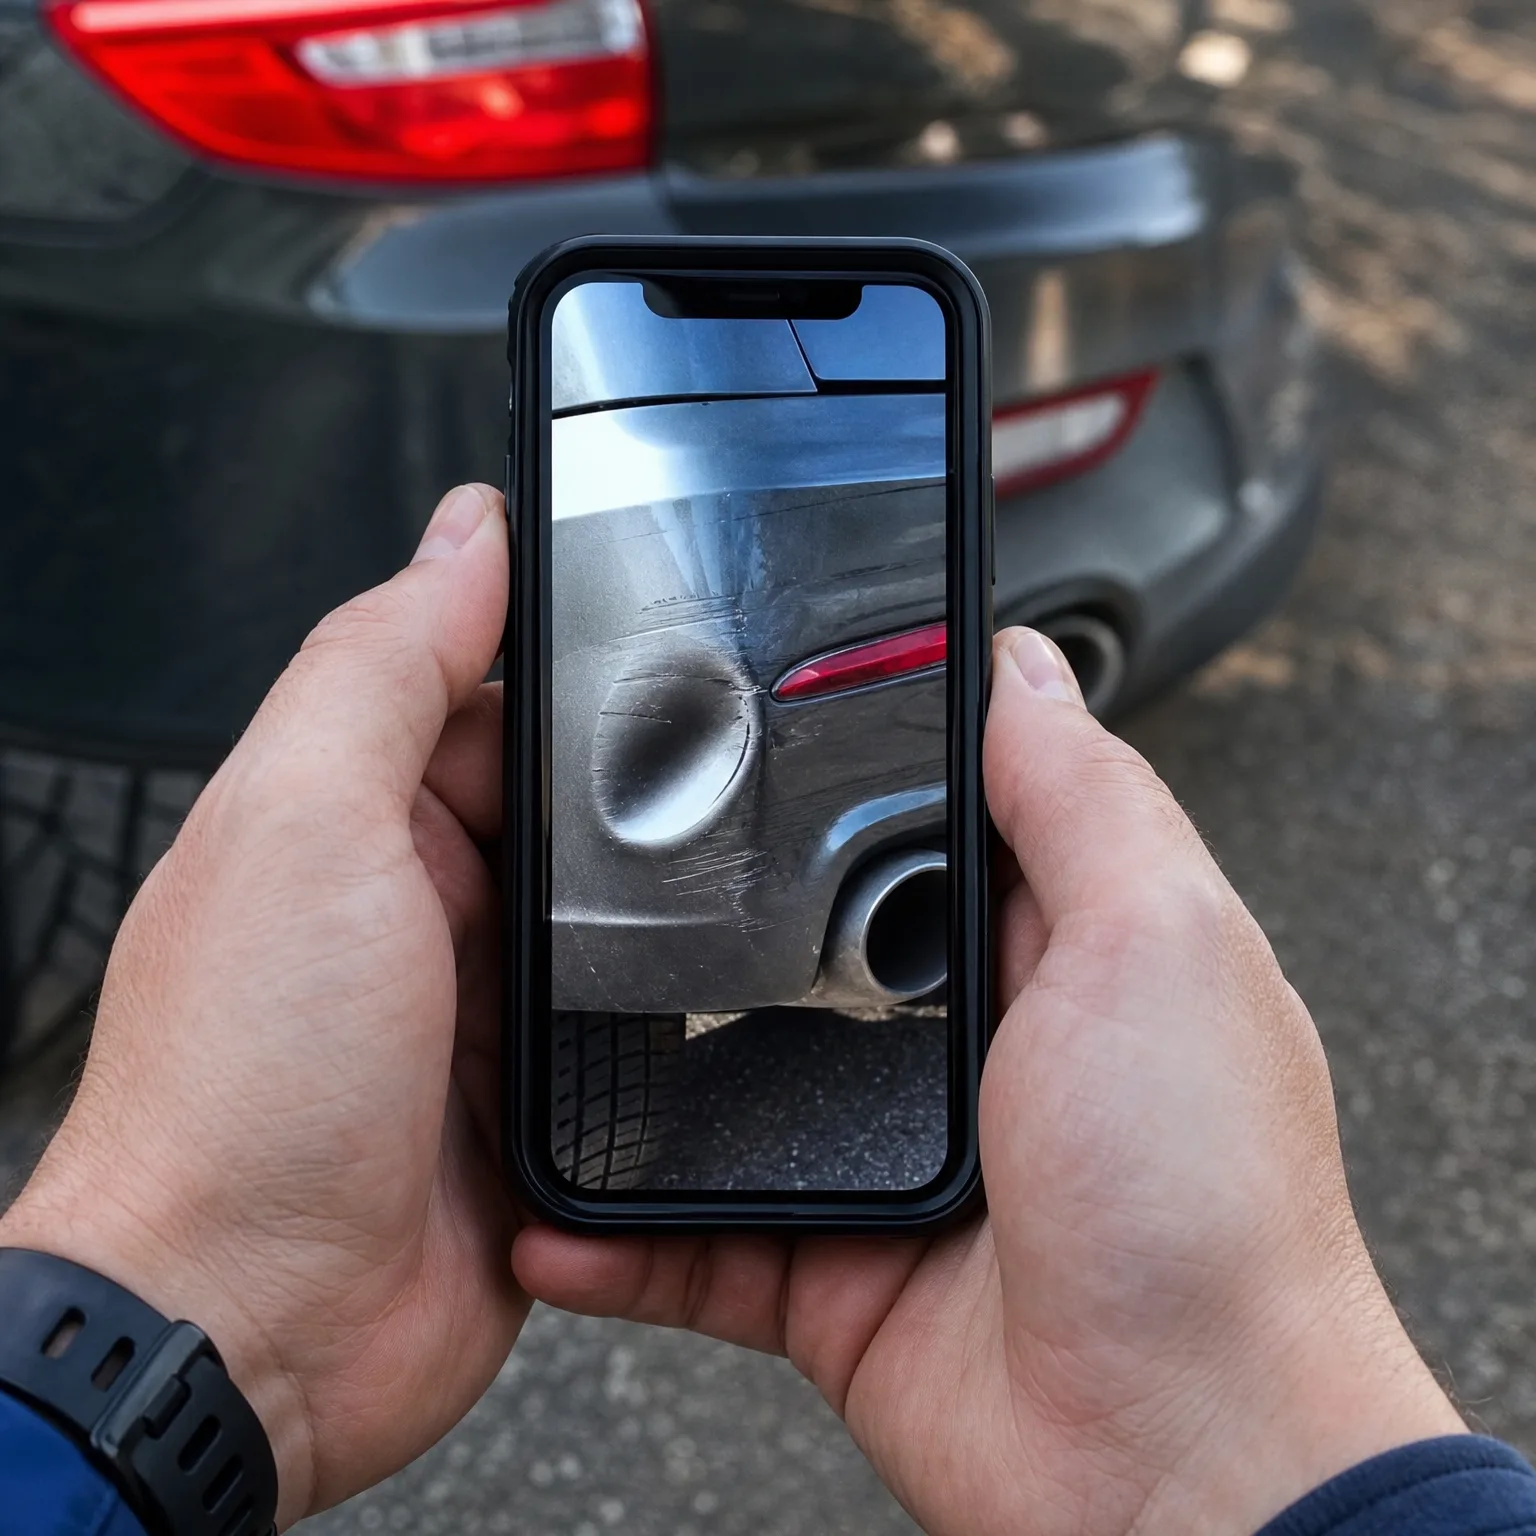
Someone financed a car with a small down payment and a long loan term to keep the monthly payment low. Two years in, another driver ran a light and totaled it. The insurer's valuation came back lower than expected because the car had higher mileage than average for its age, and the loan balance was still substantial since most of the early payments had gone toward interest.
The payout covered a good portion of the loan but left a real gap. The driver hadn't added gap coverage when they financed, so they called the lender directly, explained the situation, and worked out a payment plan for the remaining balance instead of paying it in one lump sum. On their next car, they added gap coverage the same day they signed the loan, since the new loan had the same small down payment and long term that created the problem the first time.
A low monthly payment on a long loan can quietly set you up to owe money on a car that no longer exists.