When to Decline Collision Coverage
Decline collision only when your car is worth so little that a payout wouldn't cover much more than your deductible.
Free to compare
Why this comes down to your car's value, not your new baby
Collision coverage pays to repair or replace your own car after an accident you caused, regardless of fault. The payout is always capped at your car's actual cash value, minus your deductible. So the real question is never about the baby, it's about what your car is worth right now and what you'd get back if it were totaled tomorrow.
If your car is old enough that its cash value is low, you might pay a full year of collision premiums for a payout that barely covers a used transmission. In that case the coverage is quietly expensive for what it protects. But if you're financing or leasing the car, your lender almost always requires collision and comprehensive coverage until the loan is paid off, so this decision may not be yours to make yet.
Having a baby changes your finances and your risk tolerance, but it doesn't change what the car itself is worth. A new car seat, a second vehicle, or a shift to one income are reasons to look hard at your whole policy, but they're reasons to raise liability limits or add coverage for the people in the car, not reasons to drop collision on a car that still has real value.
The exception is when the math genuinely doesn't work anymore. A car worth very little, fully paid off, with a driver who could absorb the cost of replacing it out of pocket, is a reasonable place to drop collision and redirect that premium toward coverage that actually protects your family in the seats.
What to check before you drop it
- Your car's cash value Look up what your specific car would sell for used, not what you paid. If that number is low, collision coverage may cost more over time than it would ever pay out.
- Any loan or lease terms If you're still financing or leasing, your lender likely requires collision coverage. Check your loan agreement before you consider dropping anything.
- Your emergency savings If you drop collision, you're betting you could replace the car yourself after a bad accident. Make sure that number feels real now that a baby is part of your budget.
- Your liability limits Before cutting collision, confirm your liability and medical limits are high enough to protect everyone riding with you, including your child.
- How you'd use the payout If your car was totaled tomorrow, would you replace it with something similar or go without a second car for a while? That answer tells you how much the coverage is really worth.
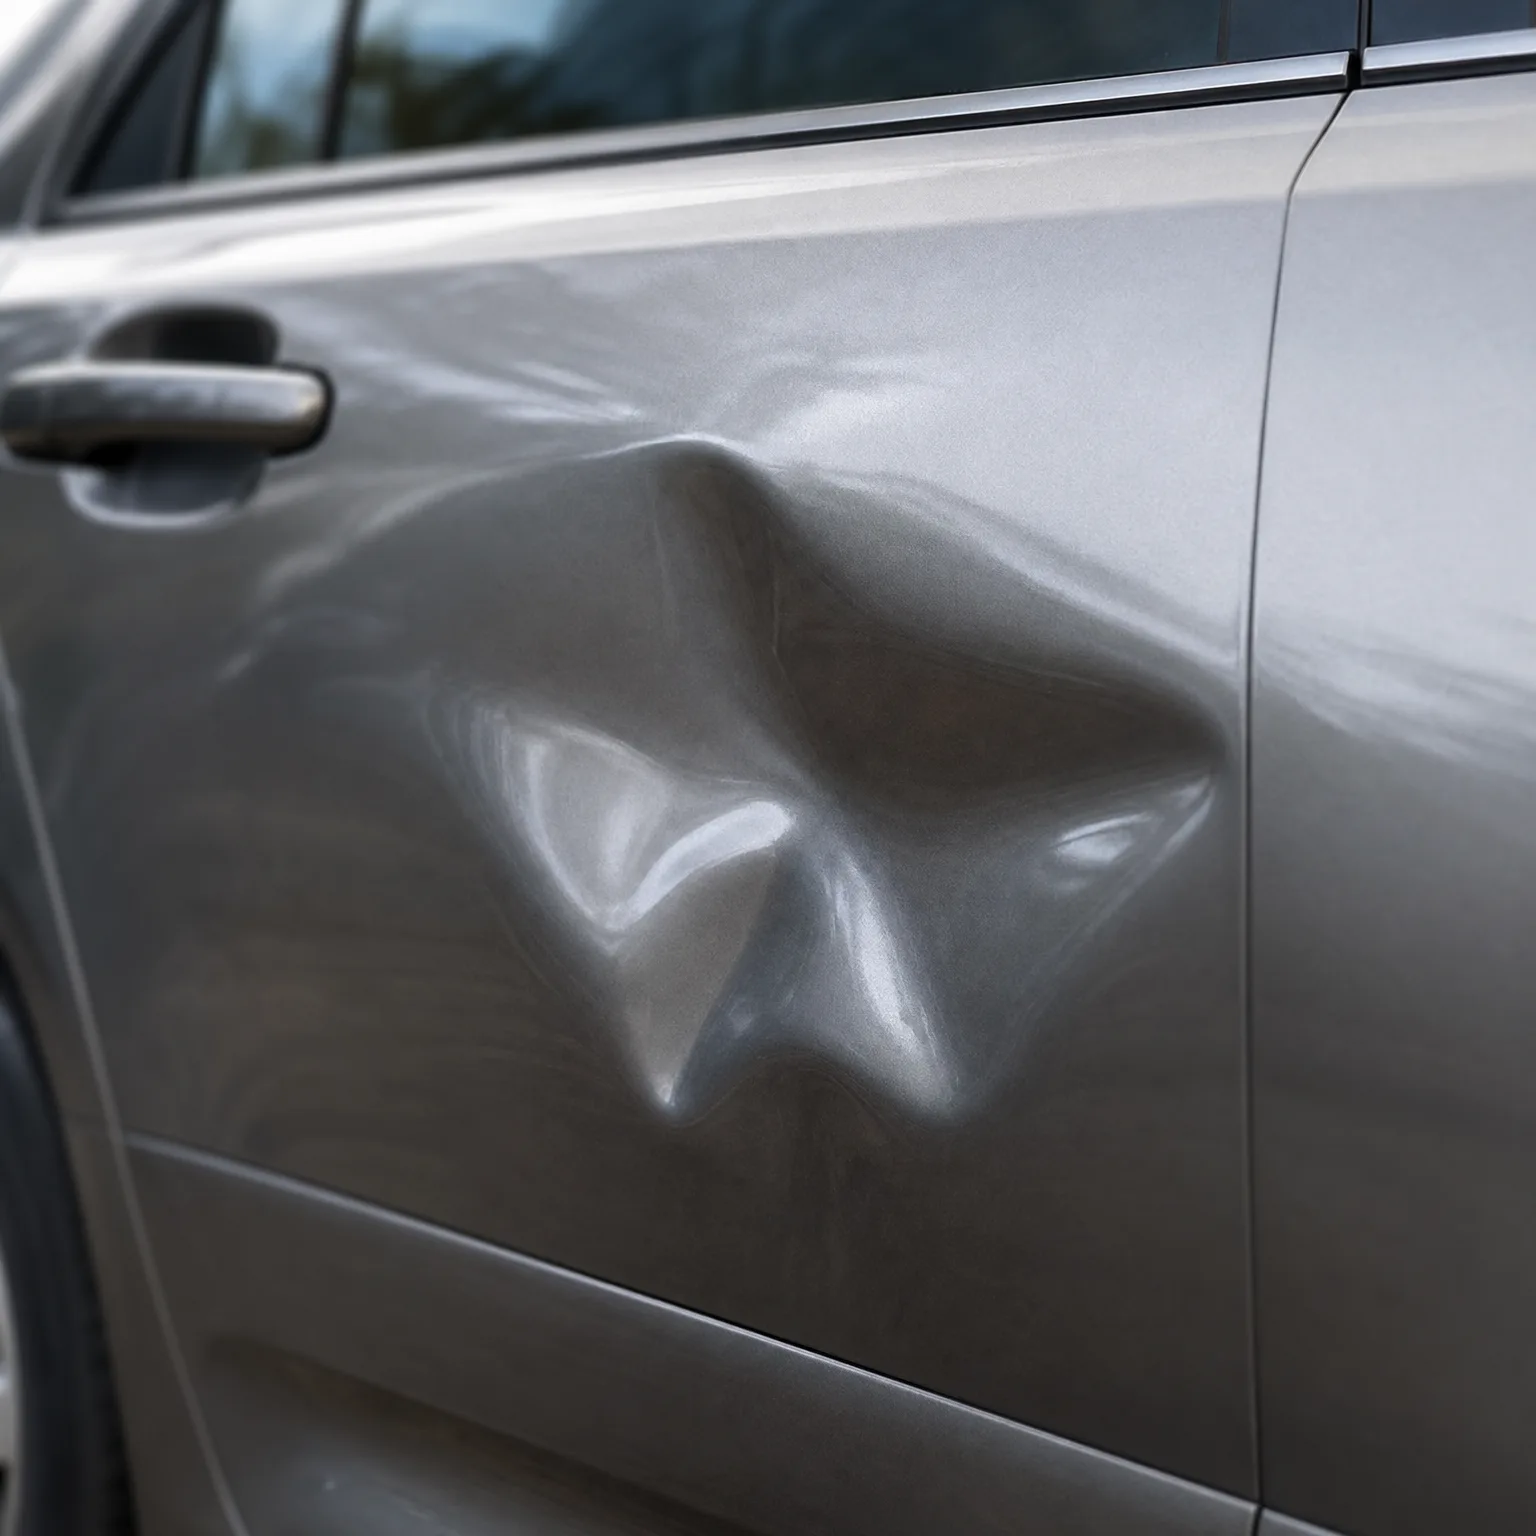
A family deciding on an older paid-off car
A couple expecting their second child were down to one income during parental leave and looking for ways to trim the budget. They had two cars, a newer one they were still financing and an older sedan they'd paid off years ago, now worth very little on the used market. The financed car legally had to keep collision coverage, so that wasn't a choice. But the older sedan was a different story.
They checked its value, confirmed they had enough savings set aside to replace it if it were ever totaled, and realized the collision premium on that car cost more each year than a used replacement engine would. They dropped collision on the older car, kept liability coverage on it, and used part of the savings to raise the liability and medical limits on the financed car, the one that would actually be carrying their kids most often. The decision freed up money without leaving anyone less protected where it mattered.
Compare quotes now that you know which car still needs collision coverage and which one doesn't.
Does having a baby mean I need more car insurance coverage?
It often means you need higher liability and medical limits, not more types of coverage. A dependent raises what you stand to lose if you're sued after an accident, so insurers and financial advisors commonly suggest reviewing your liability limits when your household grows. Check your current limits against your assets and future earnings. If you have significant savings or a second income returning after leave, the right limit changes too.
What happens to a car seat after an accident, even a minor one?
Most manufacturers recommend replacing a car seat after any moderate or severe crash, and many recommend it after any crash at all, regardless of visible damage. Check your car seat's manual for its specific policy, since it varies by manufacturer. Some insurers will cover a replacement car seat as part of a claim, so ask your insurer directly rather than assuming it's excluded or included.
Should I add my newborn to my car insurance policy?
You don't add an infant as a driver, but you should tell your insurer about the new dependent, since it can affect your eligibility for certain discounts or household rate adjustments. Check whether your insurer asks about household size or dependents for underwriting. If you're switching to a family vehicle or a different primary car, that's the bigger trigger to call your insurer, not the baby itself.
This decision was never about the baby. It's about what your car is worth, so decide based on that number.